Home Insurance Rates by State in 2026: All 50 States Ranked
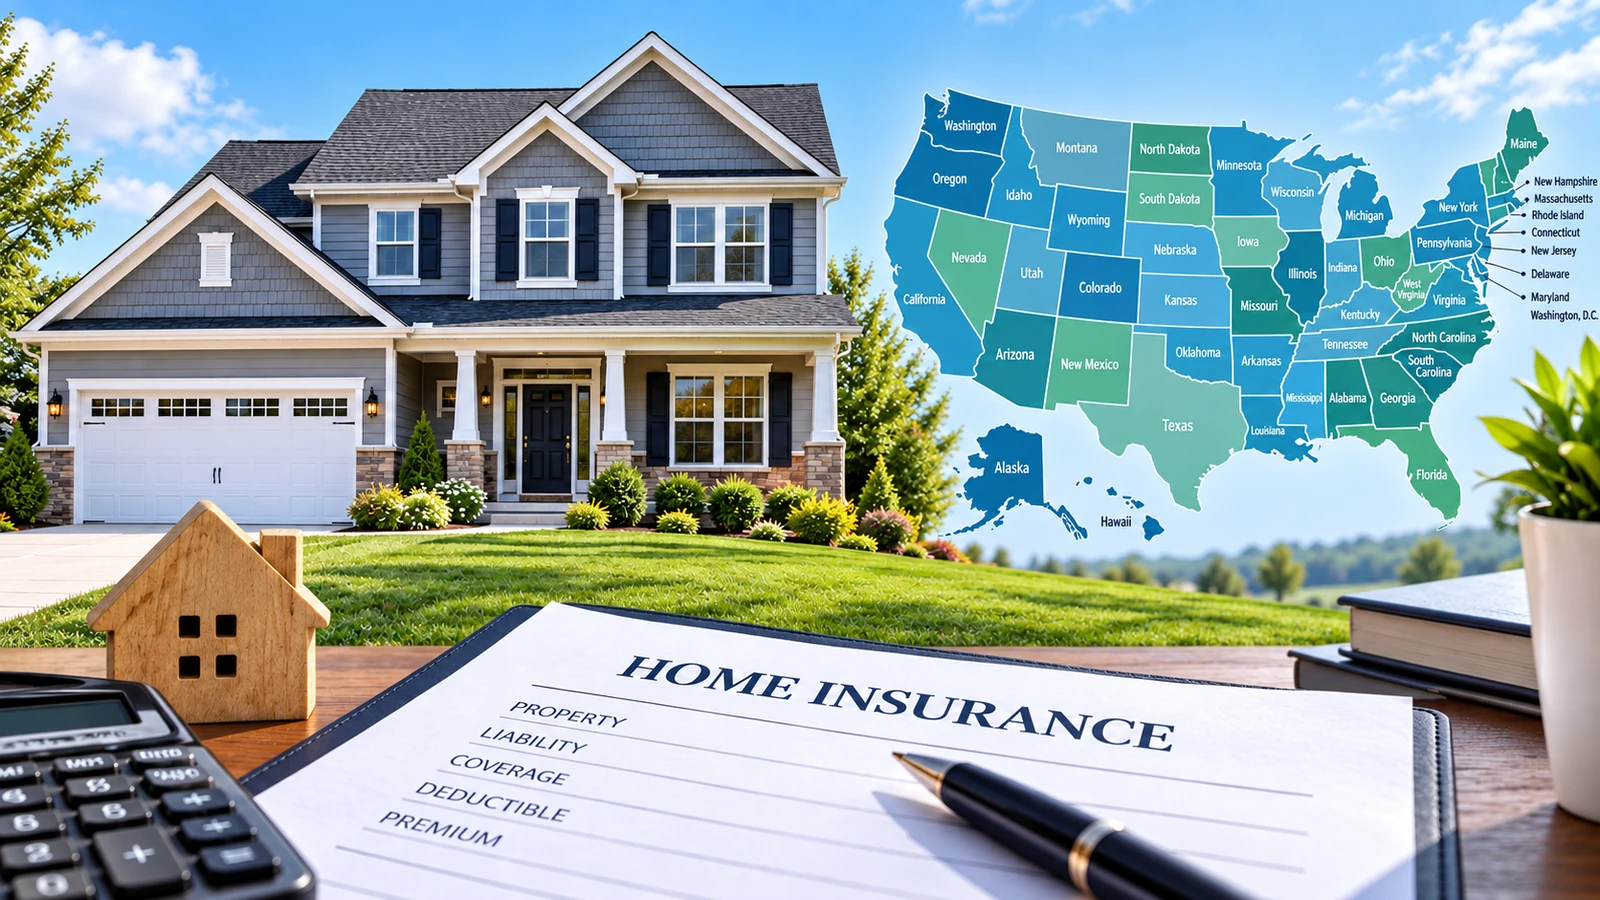
Homeowners insurance can change the economics of owning a home by thousands of dollars a year depending on where you live. Under one standardized 2026 benchmark based on modeled quotes, the average annual premium ranges from $928 in Hawaii to $5,533 in Oklahoma, a spread of $4,605 for otherwise comparable coverage assumptions.
This ranking of home insurance rates by state uses LendingTree’s current 2026 analysis of nonbinding Quadrant Information Services quotes. The benchmark is a policy with $400,000 in dwelling coverage and a $1,000 deductible, along with standardized limits for other structures, personal property, loss of use, liability, and guest medical payments.
The national average under that benchmark is $2,628 a year, or about $219 a month. These figures are useful for comparing states, but they are not quotes for a particular home.
For broader research on market conditions that affect homeownership costs, explore U.S. Housing Markets. For additional state-level comparisons, see U.S. States.
What Homeowners Insurance Rates by State Mean
In everyday use, people often say “home insurance rate” when they mean the price of a homeowners policy. That is how the term is used in this ranking.
The figures below are modeled average annual premiums, not a list of regulatory rate filings approved by state insurance departments. A filed rate change describes how an insurer’s pricing may change; an average premium estimate describes the dollar cost produced by a particular set of coverage and property assumptions.
The distinction matters because homeowners insurance is highly property-specific.
For a fair state comparison, the coverage assumptions have to stay consistent. LendingTree’s primary 2026 dataset uses:
- $400,000 in dwelling coverage;
- $40,000 for other structures;
- $200,000 for personal property;
- $80,000 for loss of use;
- $100,000 in personal liability coverage;
- $5,000 in guest medical payments; and
- a $1,000 deductible.
The $400,000 dwelling limit should not be read as a $400,000 home price. Dwelling coverage is intended to reflect the cost of rebuilding the structure, which can differ substantially from the property’s market value because market value also reflects land, location, supply, demand, and other factors.
Home Insurance Rates by State in 2026
| Rank | State | Average Annual Premium | Monthly Equivalent | Difference vs. U.S. Average |
|---|---|---|---|---|
| 1 | Oklahoma | $5,533 | $461 | +111% |
| 2 | Nebraska | $5,519 | $460 | +110% |
| 3 | Colorado | $4,717 | $393 | +79% |
| 4 | Kansas | $4,595 | $383 | +75% |
| 5 | Texas | $4,458 | $372 | +70% |
| 6 | Arkansas | $3,902 | $325 | +48% |
| 7 | Tennessee | $3,757 | $313 | +43% |
| 8 | South Dakota | $3,637 | $303 | +38% |
| 9 | Alabama | $3,614 | $301 | +38% |
| 10 | Kentucky | $3,495 | $291 | +33% |
| 11 | Iowa | $3,492 | $291 | +33% |
| 12 | South Carolina | $3,477 | $290 | +32% |
| 13 | New Mexico | $3,242 | $270 | +23% |
| 14 | Mississippi | $3,154 | $263 | +20% |
| 15 | Minnesota | $3,150 | $262 | +20% |
| 16 | Florida | $3,046 | $254 | +16% |
| 17 | Montana | $3,021 | $252 | +15% |
| 18 | Illinois | $2,987 | $249 | +14% |
| 19 | Indiana | $2,940 | $245 | +12% |
| 20 | Georgia | $2,939 | $245 | +12% |
| 21 | Missouri | $2,936 | $245 | +12% |
| 22 | Louisiana | $2,903 | $242 | +10% |
| 23 | North Carolina | $2,874 | $240 | +9% |
| 24 | Virginia | $2,762 | $230 | +5% |
| 25 | North Dakota | $2,751 | $229 | +5% |
| 26 | Connecticut | $2,595 | $216 | -1% |
| 27 | Michigan | $2,545 | $212 | -3% |
| 28 | Arizona | $2,455 | $205 | -7% |
| 29 | Wyoming | $2,396 | $200 | -9% |
| 30 | Maryland | $2,345 | $195 | -11% |
| 31 | Ohio | $2,232 | $186 | -15% |
| 32 | Rhode Island | $2,165 | $180 | -18% |
| 33 | West Virginia | $2,117 | $176 | -19% |
| 34 | Idaho | $1,975 | $165 | -25% |
| 35 | Wisconsin | $1,897 | $158 | -28% |
| 36 | Pennsylvania | $1,893 | $158 | -28% |
| 37 | Utah | $1,858 | $155 | -29% |
| 38 | Massachusetts | $1,836 | $153 | -30% |
| 39 | Nevada | $1,829 | $152 | -30% |
| 40 | Washington | $1,756 | $146 | -33% |
| 41 | New Jersey | $1,606 | $134 | -39% |
| 42 | New York | $1,587 | $132 | -40% |
| 43 | California | $1,574 | $131 | -40% |
| 44 | Alaska | $1,519 | $127 | -42% |
| 45 | Oregon | $1,518 | $126 | -42% |
| 46 | Maine | $1,433 | $119 | -45% |
| 47 | Delaware | $1,320 | $110 | -50% |
| 48 | New Hampshire | $1,150 | $96 | -56% |
| 49 | Vermont | $1,047 | $87 | -60% |
| 50 | Hawaii | $928 | $77 | -65% |
Source: LendingTree, Average Home Insurance Costs in 2026, updated August 26, 2026 and based on nonbinding Quadrant Information Services quotes obtained in February 2026 for sample homes in every U.S. ZIP code. Washington, D.C. is excluded so this article ranks the 50 states only.
Monthly equivalents are annual premiums divided by 12 and rounded to the nearest dollar. Differences from the U.S. average compare each state’s annual premium with the $2,628 national benchmark and are rounded to the nearest whole percentage point.
One useful dividing line is near the middle of the table. North Dakota, at $2,751, is about 5% above the national average, while Connecticut, at $2,595, is about 1% below it. Exactly 25 states in this dataset fall above the national benchmark and 25 fall below it.
States With the Highest Home Insurance Rates
Several of the highest-cost states face substantial severe-weather exposure. Thunderstorms, hail, tornadoes, wind and other catastrophe losses can combine with rebuilding costs and other local factors to make homeowners coverage more expensive.
The 10 highest-cost states are:
- Oklahoma: $5,533 a year
- Nebraska: $5,519
- Colorado: $4,717
- Kansas: $4,595
- Texas: $4,458
- Arkansas: $3,902
- Tennessee: $3,757
- South Dakota: $3,637
- Alabama: $3,614
- Kentucky: $3,495
Oklahoma and Nebraska stand out. Their modeled premiums are both more than double the $2,628 national benchmark, and only $14 separates them in this dataset.
That does not mean every homeowner in Oklahoma or Nebraska will pay more than every homeowner elsewhere. State averages flatten large differences between ZIP codes, construction types, insurers, deductibles, and individual property risks.
States With the Lowest Home Insurance Rates
At the lower end of home insurance rates by state, Hawaii has the lowest modeled average premium at $928 a year, followed by Vermont at $1,047 and New Hampshire at $1,150.
The 10 lowest-cost states are:
- Hawaii: $928 a year
- Vermont: $1,047
- New Hampshire: $1,150
- Delaware: $1,320
- Maine: $1,433
- Oregon: $1,518
- Alaska: $1,519
- California: $1,574
- New York: $1,587
- New Jersey: $1,606
Low statewide averages need context. They do not necessarily mean every major hazard is included in a standard policy or that every homeowner can obtain comparable coverage at that price.
Hawaii is a good example. The Hawaii Insurance Division notes that hurricane and flood damage may require separate coverage or endorsements rather than being covered by a standard homeowners policy. That is one reason a headline premium should never be interpreted as the total cost of insuring every peril a property may face.
The Gap Between the Highest and Lowest States
The difference between Oklahoma and Hawaii is $4,605 a year under the same standardized benchmark.
Put another way, Oklahoma’s $5,533 average is almost six times Hawaii’s $928 average.
On a monthly basis, the comparison is roughly:
- Oklahoma: $461 a month
- Hawaii: $77 a month
- Difference: about $384 a month
That gap is large enough to affect a household’s recurring ownership budget. It also shows why insurance deserves to be considered alongside mortgage payments, property taxes, maintenance, utilities, and association fees when comparing places to buy a home.
But the comparison is still a benchmark, not a forecast. A specific high-risk property in a relatively inexpensive state can cost far more to insure than a lower-risk property in a state with a higher average.
Why Home Insurance Rates Differ So Much by State
Insurance companies price policies around expected claims and the cost of paying those claims. Geography matters because the likelihood and severity of losses are not evenly distributed across the country.
Several forces can move state averages:
Severe weather and catastrophe exposure. Wind, hail, hurricanes, wildfire, tornadoes, winter storms, and other events can create large insured losses. Different states face different combinations of hazards, and risk can vary sharply within a state.
Rebuilding costs. Insurance is concerned with the cost to repair or rebuild a structure after a covered loss. Labor, materials, building codes, contractor availability, and local construction practices can all affect that cost.
Home characteristics. Age, construction type, roof condition, square footage, electrical or plumbing systems, and other features can change expected claim costs.
Deductibles and coverage choices. Higher limits generally cost more. A higher deductible can lower the premium while shifting more of a potential loss to the homeowner.
Local claims history and insurer pricing. Companies do not all price the same risk identically. Their claims experience, underwriting appetite, catastrophe models, discounts, and portfolio concentration can produce very different quotes.
State rules and market conditions. Insurance regulation varies by state, and the number and competitiveness of insurers willing to write coverage can also differ.
The National Association of Insurance Commissioners similarly identifies location, claims history, replacement cost, deductible, home age, and other property or policyholder characteristics as factors that can affect homeowners insurance premiums.
Why Different Studies Show Different State Rankings
Search for home insurance costs by state and you may find another reputable study with numbers that do not match this table. That does not automatically mean one of the studies is wrong.
A state ranking can change when the methodology changes.
For example, two analyses might use different:
- dwelling coverage limits;
- deductibles;
- home ages or construction profiles;
- ZIP-code samples;
- insurer samples;
- quote dates;
- credit or insurance-score assumptions where permitted;
- claims-history assumptions;
- optional coverages; or
- treatment of wind, hurricane, flood, or other catastrophe-related coverage.
Even LendingTree publishes separate 2026 analyses with different dollar figures because the coverage benchmarks and research purposes differ. Its broader state-of-the-market study uses a $350,000 dwelling benchmark, while the ranking in this article consistently uses the separate $400,000 dwelling dataset.
The practical lesson is simple: compare the methodology before comparing the numbers.
A ranking is most useful when the same assumptions are applied across every state. Mixing Oklahoma from one study, Florida from another, and Hawaii from a third would produce a table that looks precise but is not methodologically consistent.
State Averages Are Not Your Actual Premium
State averages are useful for relocation research and broad affordability comparisons. They are poor substitutes for property-specific quotes.
Your premium can be affected by details such as:
- the property’s ZIP code;
- replacement cost;
- roof age and material;
- home age and condition;
- construction type;
- distance from fire protection;
- local catastrophe exposure;
- deductible;
- selected limits and endorsements;
- prior claims;
- insurance-based credit information where state law permits its use; and
- the insurer you choose.
The NAIC’s homeowners insurance guidance also emphasizes that coverage amount, construction, home age, local fire protection, and deductible can affect what a homeowner pays.
The result is that two neighbors can receive meaningfully different quotes, and two insurers can price the same house differently.
Before buying a home, obtain several quotes using the same coverage limits and deductibles. That produces a much more useful comparison than applying a statewide average directly to the property.
Dwelling Coverage Is Not the Same as Home Value
This distinction is especially important when comparing insurance with home-price data.
The $400,000 figure used in this ranking is a dwelling coverage limit. It represents the amount of insurance available for the home’s structure under the benchmark policy, not a statement that the property would sell for $400,000.
A home’s market price includes the value of land and the economics of its location. Replacement cost focuses on what it would take to rebuild the insured structure with comparable materials and labor.
That means a $700,000 home might need less than $700,000 in dwelling coverage in one market, while another property could require a high rebuilding limit despite a lower market price.
For the separate real-estate side of the comparison, see our Average Home Price by State ranking.
Home Insurance and Overall Homeowner Affordability
Insurance is only one recurring ownership expense, but in the most expensive states it can be a substantial one.
A buyer comparing Oklahoma and Hawaii, for example, should not conclude that Hawaii is automatically the more affordable housing market because its modeled insurance premium is lower. Home prices, mortgage rates, property taxes, utilities, maintenance, association costs, and local insurance needs can change the full picture.
Our Property Tax Rates by State analysis provides a separate 50-state ranking for another major recurring homeowner cost. The broader Housing Affordability hub brings these ownership pressures together, while the U.S. States hub contains additional state-level comparisons.
For hazard and resilience-related housing research, see Housing Risk, Climate & Resilience.
How This Ranking Differs From Home Insurance vs. Property Taxes
This article answers one question: how do standardized home insurance premiums compare across all 50 states?
Our Home Insurance vs. Property Taxes by State analysis answers a different question. It compares two recurring homeowner expenses side by side.
Keeping those purposes separate is important. A state can have expensive insurance and relatively low property taxes, or high property taxes and more moderate insurance costs. Combining the two too early can hide the reason one location is more expensive than another.
Use this ranking when you want the insurance picture by itself. Use the insurance-versus-property-tax comparison when you want to see how the two costs interact.
2026 Home Insurance Market Context
The high premiums in this table sit within a market that has experienced substantial price pressure in recent years.
In a separate analysis, LendingTree found that regulator-approved U.S. home insurance rates rose a cumulative 46.8% from 2020 through 2025. The annual increase peaked at 12.7% in 2024 before easing to 6.0% in 2025.
Those figures come from a different dataset and answer a different question from the 50-state premium ranking above. They measure changes in approved insurance rates over time rather than the standardized average premium for a $400,000 dwelling policy.
That distinction is worth preserving: a state can have a relatively low current average premium but still have experienced rapid percentage increases, while another can remain expensive even after a slower recent rate increase.
The NAIC has also launched a nationwide homeowners market data call intended to give regulators more granular insight into coverage, costs, availability, deductibles, and mitigation at the ZIP-code level.
Methodology
This ranking uses LendingTree’s Average Home Insurance Costs in 2026 as the sole source for the 50-state premium table.
The rates are based on an analysis of nonbinding quotes obtained from Quadrant Information Services in February 2026 for sample homes in every U.S. ZIP code.
Unless otherwise noted, the benchmark policy uses:
- $400,000 dwelling coverage;
- $40,000 other structures coverage;
- $200,000 personal property coverage;
- $80,000 loss of use coverage;
- $100,000 personal liability coverage;
- $5,000 guest medical payments; and
- a $1,000 deductible.
States are ranked from the highest annual modeled premium to the lowest. Washington, D.C. appears in the source data but is excluded here because this is a 50-state ranking.
The monthly figures are annual premiums divided by 12 and rounded to the nearest dollar. The percentage-difference column compares each state with the $2,628 U.S. annual average under the same benchmark.
The table does not combine state values from other publishers or from LendingTree studies that use different coverage assumptions.
These figures are not binding quotes, and they do not guarantee what a particular homeowner will pay. Actual pricing depends on the property, location, coverage, insurer, underwriting factors, and applicable state rules.
This methodology keeps home insurance rates by state comparable by applying the same coverage assumptions across all 50 states.
For broader standards on ranking construction, source comparability, data periods and methodological limitations, see Data & Ranking Methodology.
Questions About Home Insurance Rates by State
Which state has the highest home insurance rate?
Oklahoma has the highest modeled average premium in the LendingTree dataset used for this ranking at $5,533 a year for the standardized $400,000 dwelling-coverage benchmark. Nebraska is a close second at $5,519.
Which state has the lowest home insurance rate?
Hawaii has the lowest modeled average premium at $928 a year under the same benchmark, followed by Vermont at $1,047 and New Hampshire at $1,150.
Why do state rankings differ between insurance studies?
The rankings can differ because studies use different dwelling limits, deductibles, sample homes, ZIP codes, insurers, homeowner assumptions, quote dates, and coverage structures. Comparing the methodology is essential before comparing state figures.
Is a state average what I will pay?
No. A state average is a benchmark. Your actual premium depends on the specific property, ZIP code, replacement cost, deductible, coverage choices, claims history, insurer, and other underwriting factors.
Does $400,000 in dwelling coverage mean a $400,000 home value?
No. Dwelling coverage is designed around the estimated cost to rebuild the structure after a covered loss. Market value also includes land and location-related value, so the two numbers can be very different.
Are these actual 2026 premiums?
They are 2026 modeled average premiums based on nonbinding Quadrant Information Services quotes obtained in February 2026 under standardized policy assumptions. They are not guaranteed premiums for every homeowner or property.
Use State Averages as a Starting Point, Not a Quote
The difference between $5,533 in Oklahoma and $928 in Hawaii shows how much location can matter even when the benchmark coverage is held constant.
For someone comparing places to buy, that makes statewide insurance costs worth checking early, not after a purchase contract is already in place.
Still, the final decision should be based on quotes for the actual property. Use these home insurance rates by state as a starting point for comparing the broad cost environment, then obtain quotes for the actual property using equivalent limits, deductibles, and endorsements.
For the next step, see our Home Insurance vs. Property Taxes by State analysis to compare two major recurring homeowner expenses.
![Modern two-story U.S. home illustrating an ]average home size by state](https://realestatelynx.com/storagelynx/2026/09/average-home-size-by-state.webp)